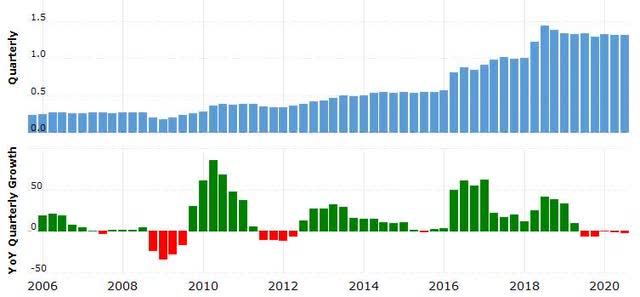
- Microchip has seen revenue come under pressure for several quarters, but it’s now calling for the bottom in its outlook with revenue growth set to take off in CY2021.
- Microchip sees an increasing order backlog as evidence of an impending upturn, but there may be more than meets the eye to recent ordering patterns.
- A combination of factors conspired to put Microchip in a difficult position with debt servicing at the top of the list.
- Microchip may have set in motion a future correction, at a time when it needs growth to get out of the predicament it’s been in for the last 2-3 years.
The last two to three years have not been kind to Microchip Technology Incorporated (MCHP). The Microsemi acquisition, the U.S.-China trade war and COVID-19 all conspired to cause problems for Microchip. So much so that Microchip’s credit ratings came under pressure and the company was forced to enact some drastic measures like cutting salary. However, Microchip is now confident the bottom is in after the latest quarterly results. But Microchip may be misreading market signs. Why will be covered next.
Q2 FY2021 quarterly report
Results were better than expected. While Q2 revenue decreased by 2.1% YoY to $1.3B, non-GAAP net income increased by 13.9% to $416.4M as shown below. Note that the GAAP numbers for net income and EPS were negatively affected by accounting adjustments related to prior acquisitions, which throw off the quarterly comparisons. FPGAs were the standout performers among product lines with 16.3% YoY growth in revenue, followed by microcontrollers with 0.8% YoY growth. LMO was flat in Q2 and analog underperformed by falling 8.2% YoY.
| (Non-GAAP) | Q2 FY2021 | Q1 FY2021 | Q2 FY2020 | QoQ | YoY |
| Net sales | $1,309.5M | $1,309.7M | $1,337.8M | – | (2.1%) |
| Gross margin | 62.2% | 61.7% | 62.2% | 50bps | – |
| Operating income | $513.8M | $505.2M | $490.8M | 1.7% | 4.7% |
| Net income | $416.4M | $401.9M | $365.7M | 3.6% | 13.9% |
| EPS | $1.56 | $1.56 | $1.43 | – | 9.1% |
| (GAAP) | |||||
| Net sales | $1,309.5M | $1,309.7M | $1,337.8M | – | (2.1%) |
| Gross margin | 61.7% | 61.0% | 61.9% | 70bps | (20bps)- |
| Operating income | $226.2M | $218.3M | $183.6M | 3.6% | 23.2% |
| Net income | $73.6M | $123.6M | $108.9M | (40.5%) | (32.4%) |
| EPS | $0.27 | $0.48 | $0.43 | (43.8) | (37.2%) |
Source: Microchip Form 8-K
Guidance calls for Q3 revenue of $1.310-1.375B, an increase of 4.3% YoY at the midpoint. Revenue in the December quarters tends to decline by 2-3% QoQ due to seasonality. But the forecast implies a sequential increase of 0-5% this time around, despite the loss of the 1% revenue contribution from Huawei due to U.S. sanctions.


