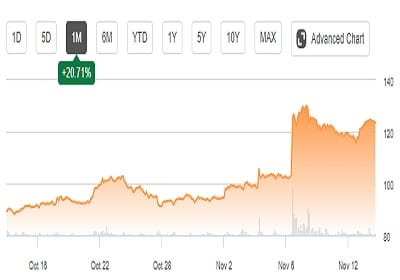
Looking to buy companies within sectors that have seen significant declines can be a successful strategy if said sector has the potential to be undervalued or rebound. Expedia Group, Inc. (NASDAQ:EXPE) has the potential to be one of these types of companies. With a strong history of growth before the pandemic and a vast portfolio of brands, Expedia has the potential to rebound financially over the next year. Low demand for travel due to the COVID-19 pandemic has resulted in losses for 2020 and increased debt load to make it through the year. Although a rebound in financials is attainable, especially with news of a possible vaccine, Expedia is now highly leveraged, still has major industry uncertainties, and does not provide any margin of safety for these risks.
Over the past five years, Expedia has posted high growth rates across the board. Revenue has grown at a CAGR of 12.59% and operating income at 16.88%. Net income has seen steady growth of 18.97% per year from 2016 to 2019. But the best metric to see growth is gross bookings. Gross bookings have increased at a clip of 12.21%, while the revenue margin has stayed consistent at around 11%. But, over the past five years, the world economy was in a very strong expansion period, with leisure and business travel at highs. This all changed when the COVID-19 pandemic shut down many of the world’s economies and significantly reduced the movement of people.
READ FULL ARTICLE HERE


