Summary
- I continue to be impressed by CoStar’s ability to sustain growth and margin expansion through COVID.
- Post-3Q, CoStar remains on track for its FY23 targets given the extensive runway and the margin-accretive shift toward Marketplace.
- Backed by a ~$3.9bn war chest, expect more inorganic growth down the line as well.
- Relative to its FY23 targets, I view CoStar as a very investable growth story.
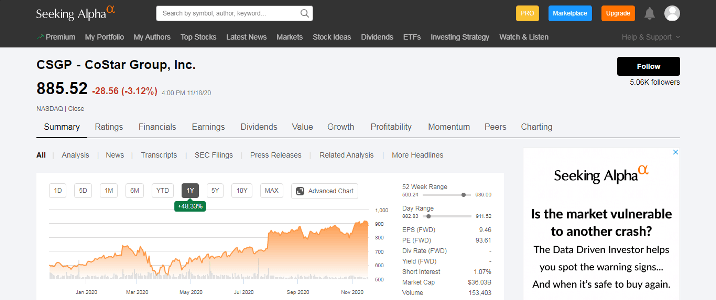
CoStar stock has outperformed YTD, but I think this rally still has legs. Yes, the multiple is high, but there’s ample growth potential and visibility to boot – the company derives the vast majority of its revenue from subscription-based services and has sustained exceedingly high renewal rates over the years. Plus, CSGP is tackling a massive TAM (digitizing the real estate industry). Growth, margin expansion, and high cash conversions are a good combination in any investment, and I believe CSGP has them in spades. Relative to the FY23 targets, which seem very much within reach, the risk/reward strikes me as favorable here.


