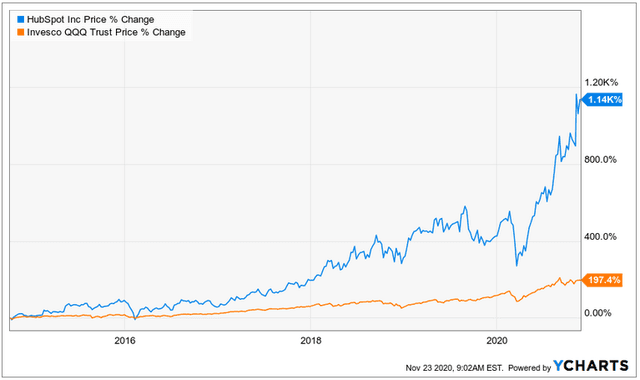
- HubSpot, a stalwart of the digital marketing software sector, delivered a strong acceleration in growth in Q3.
- The company has also been cashflow positive for some time now.
- We believe the company will continue to benefit from the shift to digital marketing.
- We rate the stock at Buy-Long Term Hold as a result.
DISCLAIMER: This note is intended for US recipients only and in particular is not directed at, nor intended to be relied upon by any UK recipients. Any information or analysis in this note is not an offer to sell or the solicitation of an offer to buy any securities. Nothing in this note is intended to be investment advice and nor should it be relied upon to make investment decisions. Cestrian Capital Research, Inc., its employees, agents or affiliates, including the author of this note, or related persons, may have a position in any stocks, security or financial instrument referenced in this note. Any opinions, analyses, or probabilities expressed in this note are those of the author as of the note’s date of publication and are subject to change without notice. Companies referenced in this note or their employees or affiliates may be customers of Cestrian Capital Research, Inc. Cestrian Capital Research, Inc. values both its independence and transparency and does not believe that this presents a material potential conflict of interest or impacts the content of its research or publications.
Doesn’t Eat Its Own Cooking
Given that HubSpot, Inc is a leader in digital marketing software, it’s rather surprising to us at least that it’s not a more high-profile company. You rarely see it made mention of among the cloud-sector commentariat on Twitter and elsewhere. A little long in the tooth, HUBS was established in 2006, making it a fully paid-up member of the original Internet 2.0 cohort, alongside Workday and others born at that time. Likely due to its age you don’t see the name bandied around so much in breathless recants of hot cloud stocks.


