Summary
- Mastercard released its latest volume data for the last 4 weeks on Tuesday night, showing “relatively steady” trends from Q3 2020.
- Global volumes remained about 3% higher year on year so far in November, despite the resumption of COVID-19 restrictions in key markets.
- Cross-border volume has stayed at the same level as Q3, due to continuing travel restrictions, except in low-margin intra-Europe volume.
- We expect EBIT will show a 25% year-on-year decline in Q4, but the end of COVID-19 is now in sight, and travel is expected to recover in H2 2021.
- At $342.39, Mastercard shares can deliver a total return of 36% (10.0% annualised) in just over 3 years. We re-iterate our Buy rating
Introduction
We review our investment case on Mastercard based on the latest volume data released on Tuesday night (November 24) and other developments since our last update in September.
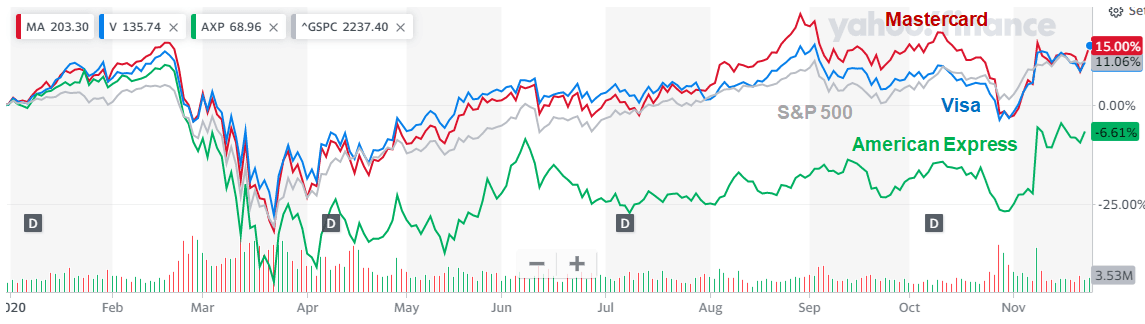
Since we initiated our coverage with a Buy rating in March 2019, MA shares have returned 46.5% (including dividends). During 2020 year to date, MA shares have returned 15.2%, outperforming the S&P 500 index, was far ahead of “value” play American Express but was behind PayPal (whose shares have risen around 90%):


