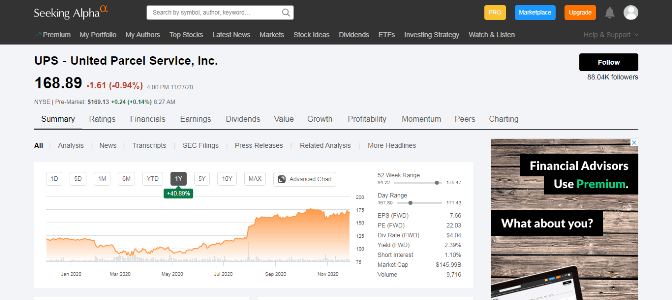
- It looks unseemly to consider buying United Parcel Service’s stock that has already risen by 48% in the current year.
- SMB volume increased by ~19% in Q3 FY20, the highest growth in the segment in over a decade and a half.
- The stock is beginning to recover from the sell-off after the Q3 FY20 results announcement, and any small dips now will be a good time to buy.
It looks unseemly to consider buying a stock that has already risen by 48% in the current year, especially when the stock price has moved between long-term highs and lows in a matter of months. But United Parcel Service (UPS) today is being driven by something more fundamental than temporary blips in demand – the logistics industry is experiencing a shift in consumer behaviour, which is likely to be permanent, and the resultant change in the way businesses are operating globally. UPS, the world’s leading distributor of small packages, will benefit from this evolution more than most other logistics providers. Even after the threat of COVID-19 recedes, e-commerce (and B2C deliveries) will remain a larger-than-before channel of distribution for companies across sectors, and UPS is set to reap the benefits of the development.


