- Tenneco appears headed for a strong FQ4 following a top and bottom-line outperformance in its latest quarter.
- Cash generation remains strong through the cycles, although debt levels also remain elevated.
- The key issue remains the longer-term transition to EVs, which Tenneco does not appear to be prepared for.
- Limited strategic optionality also adds to the longer-term concerns.
- Considering the headwinds, I see the current valuation discount as justified.
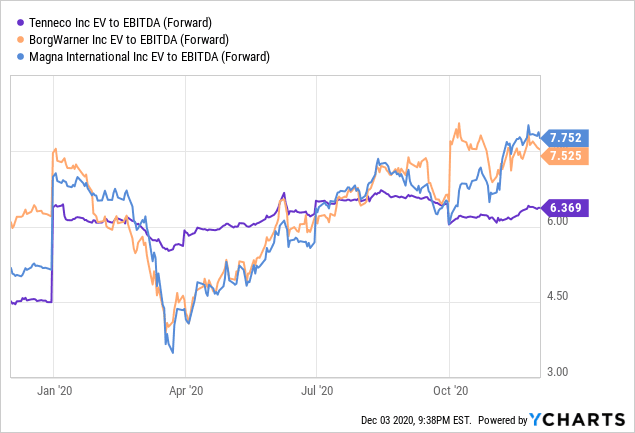
Tenneco (TEN) is a Tier-1 supplier of clean air, powertrain, and ride performance products and systems to both auto manufacturers and aftermarket customers, including the likes of General Motors (GM) and Ford (F). While Tenneco did outperform in FQ3, the key hurdle remains its outsized exposure to legacy internal combustion engine (ICE) systems. Coupled with its highly indebted balance sheet, the company’s ability to transition toward more EV-focused content appears to be challenged. Corporate actions are a step in the right direction (if they materialize) but do not address the underlying issues. Although shares the trade at a discounted c. 6x EV/EBITDA multiple, I see limited upside going forward.
FQ3 Outperformance Across the Top and Bottom Lines
Tenneco reported a relatively strong set of FQ3 results, featuring higher revenue and improved operating margins amid an uncertain macro backdrop. Although its earnings did fall short of consensus, this was largely due to unfavorable below-the-line items (mainly the higher tax rate). Nonetheless, the fact that revenue strength was broad-based across all segments was a key positive, with strong industry volumes offsetting relative underperformance in organic value-added revenue (5%pts below light vehicle production at -8% Y/Y).
Adjusted EBITDA of $388 million was also a highlight, as aggressive cost reductions led to resilient value-add margins of 11.8% (+90bps Y/Y). Of note, Powertrain and Motorparts were strong, showing Y/Y margin improvement despite lower sales. As a result, Tenneco generated $475 million in free cash flow in FQ3, on the back of strong working capital efficiency and an impressive profit flow through.
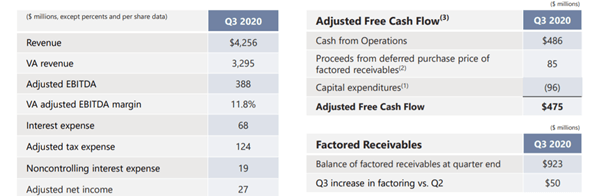
Source: Tenneco FQ3 ’20 Presentation Slides
FQ4 Guidance Points Toward a Positive Near-Term Outlook
Importantly, Tenneco’s FQ4 guidance is trending positively – EBITDA was guided to $345 million, materially ahead of consensus estimates (c. $290 million) based on implied revenue of $3,295 million. Notably, the FQ4 guide seems concentrated around the value-add adjusted EBITDA margin line, which stands at c. 10.5%, suggesting a continued improvement in execution. Also impressive is the fact that EBITDA margins are expanding c. 200bps Y/Y despite c. $50 million in austerity measures going away in the upcoming quarter.
The stronger FQ3 and even better FQ4 outlook point toward an above-consensus fiscal 2021 EBITDA outcome, even with the benefit of fiscal 2020 austerity measures fading in the year ahead. Furthermore, Tenneco’s strong cash generation (c. $475 million of FCF in FQ3, equivalent to a significant portion of its current market cap) through the cycles has been encouraging. Assuming this continues, the company should have no issues with deleveraging in the upcoming quarters. Admittedly, FCF could normalize lower in the upcoming year as FQ3 did benefit from lower capex, but Tenneco’s restructuring efforts should also help. At present, the company is on track to reap $165 million in run-rate savings for fiscal 2020 and $265 million in run-rate savings by fiscal 2021.


