- Future dividends alone cannot justify the current price of Microsoft.
- However, the DCF modeling indicates the current undervaluation of MSFT.
- 2021 will be a tough year for Microsoft and big tech companies in general.
For the past three months, Microsoft (MSFT) stock price has been in a sideways trend, showing more than 35% growth since the beginning of the year. And in my opinion, this is a good moment to reassess the fundamental potential of the company using tools such as Discounted Cash Flow and Dividend Discount models. In addition, it is necessary to identify certain risks that await this company next year.

Source: goodfon.ru
Discounted Cash Flow Model
When predicting Microsoft’s revenue for the next 10 years, I proceeded from the average expectations of analysts. In my opinion, the compound annual growth rate of 11.3% is quite adequate:
 Source: Seeking Alpha
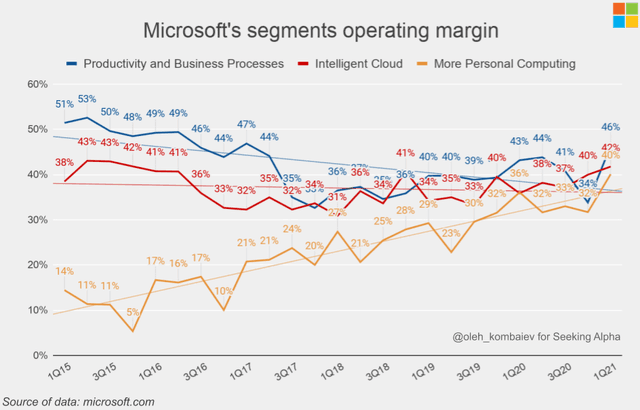
Between 2015 and 2017, the operating margins of “Productivity and Business Processes” and “Intelligent Cloud” tended to decline. The profitability growth was observed only in the “More Personal Computing” segment. But, the situation has changed over the past two years and the operating margins of all segments have begun to grow. Given this clear qualitative improvement, I included in the model only a slight decrease in operating margin from 37% to 34% in the terminal year.


