- Don’t forget we consider the mall sector higher risk, and we maintain an underweight allocation in it.
- However, we consider Simon an attractive position, especially for the higher-risk REIT investor.
- In this article, we break down the latest news and provide a realistic analysis, as well as our forecast for growth.
- We purchased another 56 shares in the Durable Income Portfolio on Dec. 4 at $89.63 per share.
- Looking for more investing ideas like this one? Get them exclusively at iREIT on Alpha. Get started today »
This article was coproduced with Williams Equity Research (“WER”)
What do we need to say about mall REITs at this point?
We all know they were already in trouble before 2020. And we all know they’ve been in much, much, much more trouble since the shutdowns and social distancing and general panic began.
Some have given up hope on them completely as a result.
Here at iREIT, we understand the reasons why – more so than most of the naysayers and gloom and doom crowd, we dare say. There are many reasons why we’re underweight on mall real estate investment trusts (REITs) right now.
However, there also are many reasons why we’re not writing off the whole subsector just yet. Nor do we expect to.
As we’ve said once, twice, and perhaps more than a dozen times now… some malls will fall apart. So some mall REITs will fail as well.
But we don’t see that fate for others, such as Simon Property Group (SPG).
It’s true this international business has been in the crosshairs of the two major crises we already alluded to: The retail apocalypse and the economic impacts of the coronavirus. Yet it’s maintained its investment-grade balance sheet anyway, and its portfolio continues to generate positive cash flow as well.
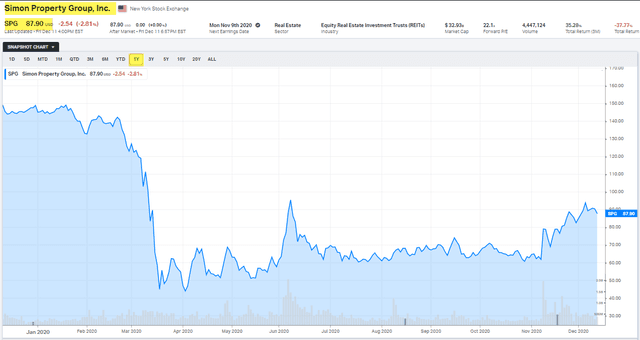
Earlier this year, Simon’s valuation was depressingly distressed anyway. Times have changed, however, and it’s well worth revisiting.

(Source)
Simon Property Group and “That” Taubman Deal
In many ways, Simon’s stock has encapsulated retail real estate’s sensitivity to the coronavirus since it collapsed back in March.
On the one hand, it entered the shutdowns on strong footing. On the other, its February agreement to buy fellow mall REIT Taubman (TCO) – which we analyzed for iREIT subscribers in a few articles as the deal seemed to sour – seemed like the worst timing possible.
This perception was only reinforced by Simon seeking financing by selling equity at $72.50.
Yet that offering was fully and enthusiastically subscribed. The stock quickly moved 15%-20% higher than the price the new equity was offered at.
Since this was an unusual situation, it’s worth analyzing a little further.


