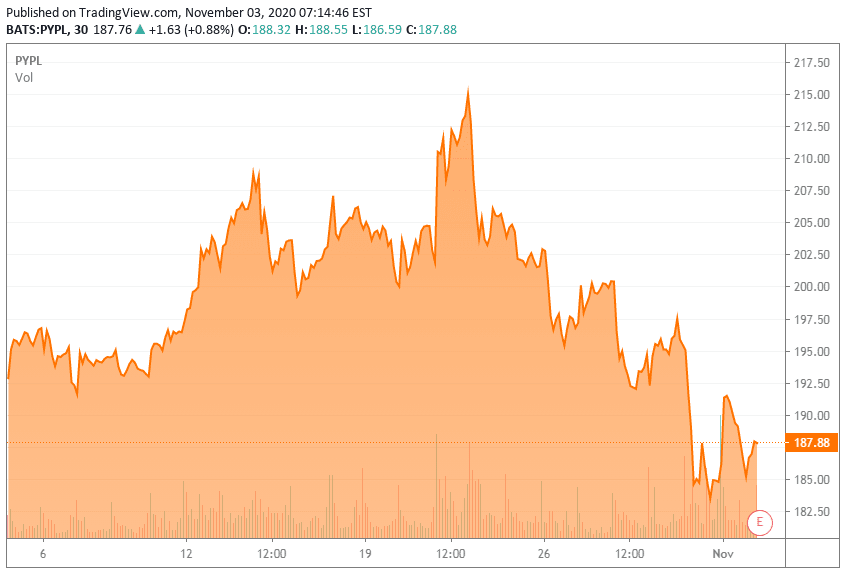
- Strong set of results, yet the stock sold off — unjustifiably so.
- The only blemish in its report was that FCF was weak this quarter.
- Nonetheless, PayPal eyes up more than $5 billion of FCF for this year.
- PayPal is not an expensive stock, and is worthwhile considering.
- Looking for more investing ideas like this one? Get them exclusively at Deep Value Returns. Get started today »
Investment Thesis
PayPal (PYPL) reported a strong set of results and guidance.
PayPal continues to push ahead with more than 20% revenue growth rates, while the stock remains priced at single digits its 2021 revenues.
For 2020, PayPal is guiding for more than $5 billion of free cash flow, leaving the stock cheaply valued at approximately 41x this year’s free cash flow. In the present overvalued stock market, this leaves PayPal’s stock cheaply valued, and worthwhile considering.
Revenue Growth Rates Are as Strong as Ever

Source: author’s calculations; **mid-point company guidance
PayPal reported strong results and raised guidance on its EPS guidance. For 2020, PayPal’s EPS guidance is now pointing towards a growth rate of 27%–28% versus approximately 25% growth it was previously guiding for at the end of Q3 2019.
The graphic above largely speaks for itself: not only is PayPal still growing strongly but it’s actually picking up top-line momentum in 2020. Yet the stock still sold off after hours.
Why Did The Stock Sell-off After Hours?
Every financial outlet wishes to report its own rationale for why stocks are reporting strong results and guidance and yet the stocks are selling off. And every investor wants a clear and concise (preferably snappy), reason for a cause and effect during these earnings reports.
Typically, I do offer my own cause and effect, as in many cases it’s quite obvious. However, in PayPal’s case, I can’t find any tangible blemishes with this report that would make me concerned.
What I would say, is that tech stocks have carried the bull market of 2020, and that many stocks have been priced in on the expectation that they are immune to the underlying economy. Thus, investors have been willing to bid up these assets, even as the detachment between Wall Street and Main Street continues to widen.
The Market is not Paying Enough Attention to Venmo
Venmo is PayPal’s digital wallet. Venmo is showing no signs of slowing down, as its Total Payment Volume was up 61%. What’s more, looking out to 2021, its revenues are forecast to reach $900 million.
Furthermore, in 2021, Venmo will start to be accretive to PayPal’s consolidated bottom line.
Even if we extrapolate Venmo’s growth rate, PayPal is unlikely to segment out its Venmo operations for some time, most likely until Venmo makes up 10% of its consolidated revenues.
Nonetheless, this is a very strong opportunity for PayPal, and one that investors are not affording enough consideration to.


