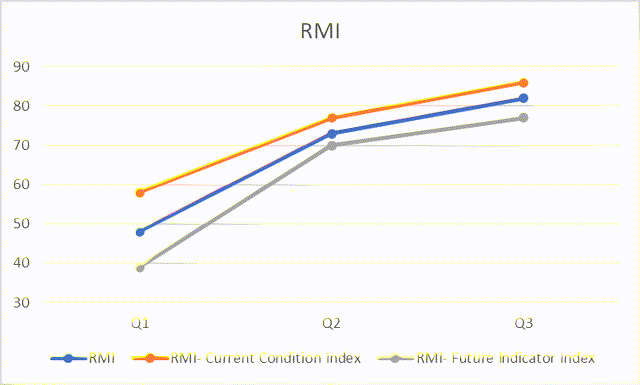
- MAS put on a good show in Q3 both on the top line, bottom line, and margin front. The balance sheet looks strong and repurchases will recommence in Q4.
- The latest RMI readings for Q3 have been strong but we could see a ceiling soon.
- Key upcoming headwinds include seasonality, high base effect, lack of inventory restocking support, higher raw material costs and investment spend, and likely weakness in key international regions.
- I do much more than just articles at The Lead-Lag Report: Members get access to model portfolios, regular updates, a chat room, and more. Get started today »
The house is no longer just a place for shelter. It has become the office, the restaurant, the classroom, the gym, and the entertainment center. – Keith Allman
Masco Corporation (MAS) is a manufacturer and distributor of branded home improvement and building products. The company reports under two segments – Plumbing Products (c.60% of group revenue) and Decorative Architectural Products (c.40% of group revenue).
A resilient Q3
Last week the company announced a good set of results. Buoyed by strong demand for its products, MAS posted a significant improvement on the top line, with sales growth of 15% in constant currency terms; compare this to Q2, where constant current sales had declined by -3%. Incidentally, its Q3 sales of $1983m also managed to beat market estimates by 7%. In addition to the increased sales volume, the company has also been resorting to strong cost control measures, and this was reflected in more than a 2% annual improvement in the Gross margin (GM) at 38%. On the operating front, operating profit grew by 43% annually, whilst margins improved by 400bps to hit 21.4%. All this was reflected in strong bottom-line growth, with EPS growing annually by 73%, and coming in 33% higher than street estimates.
Balance sheet in decent shape, divis have been increased and repurchases to resume
In September, MAS increased their dividend by c.4% to 0.14 per share; at the current share price you get a decent yield of 1%. Despite some of their operating challenges in previous years, the company has been fairly regular in paying out its dividends, which have now grown annually for 7 years on the trot. Besides, the other encouraging aspect is that they will resume their share repurchase operations sometime in Q4 with an initial target of deploying $100m. To support both the divis and the repos, a company’s balance sheet needs to be fairly resilient, and I think it’s fair to say that currently, it’s the best it has been in years. Currently, MAS has about $2.3bn in liquidity ($1.3bn of cash and $1bn of the revolver) and the net debt at $1.6bn is at the lowest level since Dec-2015 (Current net debt to EBITDA is at a very respectable 1.1x). Crucially in Q3, the company was also able to refinance their 2021 debt maturity at low rates which could potentially result in c.$4m of annual interest savings.


