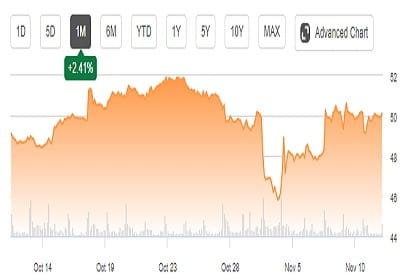
Archer-Daniels-Midland (ADM) is one of my largest, non-European food processing and commodities trading holdings. I presented my position and stance for ADM over a year ago, and have tried keeping it up to date since.
Like many companies who depend on the pricing of commodities like soybeans, corn, and other oilseeds and products, ADM’s year-over-year results depend highly on a fairly volatile market, and the international economy. This is, in particular, true with the higher focus on soybeans that’s been growing for the past few years.
In my past articles, it’s been easy to invest in ADM. The simple reason for this was the company spent almost a full year – and more, really – trading at multiples that underscored its long-term earnings potential, with a small bounce back at the end of 2019 to anything resembling a full valuation.
READ FULL ARTICLE HERE


