- Fundamentals kept moving in the right direction.
- The growth in the company’s intrinsic value justifies the strong share price appreciation.
- Long-term business prospects are still intact.
Our bullish investment case on Facebook (FB) was mainly based on the fact that advertisers will keep allocating an increasing portion of their marketing & advertising budgets online. Given the duopoly nature of the online advertising market as well as Facebook’s leading position, we expect that additional demand benefits Facebook. Besides, Facebook is also in a good position to increase ARPUs because of its best-in-class platform and product offerings. At the same time, we believe that the platform will keep attracting users and advertisers over time, especially in APAC and in the rest of the world regions. Finally, we believe that the stock offers good value as many investors are focusing on short-term noises such as regulatory & antitrust risks or IT sector overvaluation.
While many SA authors have already covered Q3 earnings, the aim of this article is not to comment (and repeat) quarterly earnings but more to show the evolution of the most important variables supporting our investment case.
First of all, the evolution of online advertising market is paramount to the investment case. Even though marketing & adverting budgets may be impacted by economic activity (less money is spent on marketing during recessions), the transition from offline to online marketing is much more stable and need to continue even during more challenging periods.
Overall ad spending will decline by 4.9% worldwide this year, a significant drop from last year’s 6.3% growth and from our pre-pandemic 2020 forecast of 7.0% growth.
Worldwide digital ad spending will achieve 2.4% growth this year, the lowest on record. Although this figure is still positive, the category has never been in single digits.
(Source: Emarketer.com)
Recent data suggest that online marketing is still gaining market share over offline marketing, which suggests that Facebook is still very well positioned to benefit from this ongoing structural change.
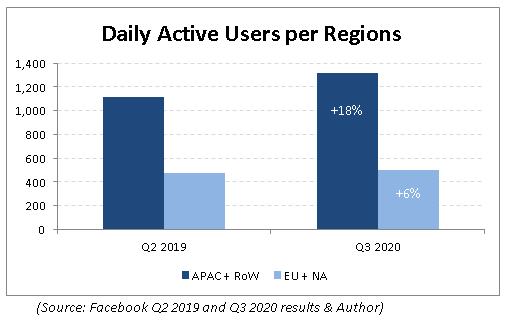
ARPUs are higher than they used to be while we wrote our bullish investment thesis in September 2019. At that time, we did expect an increase in ARPUs, mainly driven by North America and Europe, while volume growth was expected for other regions (namely APAC and Rest of the World). Given that user base is much more developed in developed economies, it makes sense to assume that advertisers have access to a much larger potential client base as well as broader data set; therefore, they are ready to pay higher prices. Given that APAC and the Rest of the World are less developed economies, with a lower penetration rate of Facebook apps, volume was expected as the main growth driver.
Looking at data, we can see that all regions have benefited from higher ARPUs. Even though APAC enjoyed the fastest growth in ARPU over the period, the ARPU development in North America and Europe has been strong as well. Volume growth was much stronger in the RoW and APAC while still positive in Europe and North America as many companies (SMEs in particular) are moving their business online.


