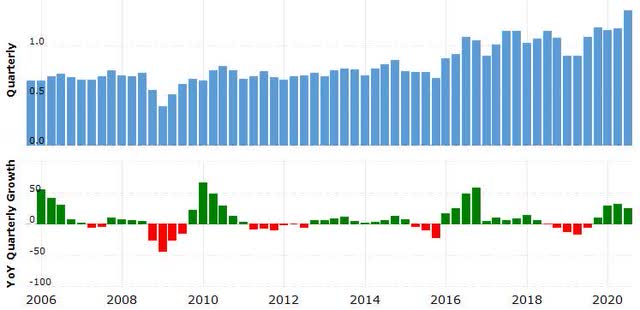
- Sales and net income grew by double digits in Q3, but Amkor may be anticipating the possibility of a slowdown in demand if Q4 guidance is any indication.
- A case could be made for long Amkor, which includes trading at lower multiples than the competition on top of double-digit growth.
- There was inventory building in certain market segments, which may have skewed the quarterly numbers by making demand seem stronger than it really is.
- The recent quarterly numbers from Amkor are an outlier and odds are the company will revert back to what it was prior to recent deviations.
Amkor Technology (AMKR) looks to be on a roll. The company posted its fourth straight record quarterly revenue when it grew sales and net income by double digits in its latest quarterly report. Yet, Amkor may not be as well off despite appearing to be hitting on all cylinders. Why will be covered next.
Q3 2020 quarterly report
Results were above the high-end of guidance. Q3 sales increased by 25% YoY to $1,354M. Bottom-line growth was even more impressive. Net income jumped by 70% YoY to $92M. Higher margins contributed to the big increase. Gross margin improved by 100 basis points YoY and operating margin by 210 basis points YoY. Good numbers throughout as shown below, but there’s more. Amkor will begin to pay a dividend starting in 2021, a sign of long-term confidence.
| (GAAP) | Q3 2020 | Q2 2020 | Q3 2019 | QoQ | YoY |
| Net sales | $1,354M | $1,173M | $1,084M | 15.43% | 24.91% |
| Gross margin | 17.8% | 16.4% | 16.8% | 140bps | 100bps |
| Operating margin | 9.4% | 7.4% | 7.3% | 200bps | 210bps |
| Operating income | $127M | $87M | $79M | 45.98% | 60.76% |
| Net income | $92M | $55M | $54M | 67.27% | 70.37% |
| EPS | $0.38 | $0.23 | $0.23 | 65.22% | 65.22% |
Source: Amkor Form 8-K
Amkor credits solid demand for the better-than-expected quarterly numbers. Specifically, the communications, automotive, and industrial markets exceeded expectations. From the Q3 earnings call:


