- CTIC recently received FDA’s accelerated approval go-ahead for pacritinib in MF patients with severe thrombocytopenia.
- This considerably reduces the risks associated with the company.
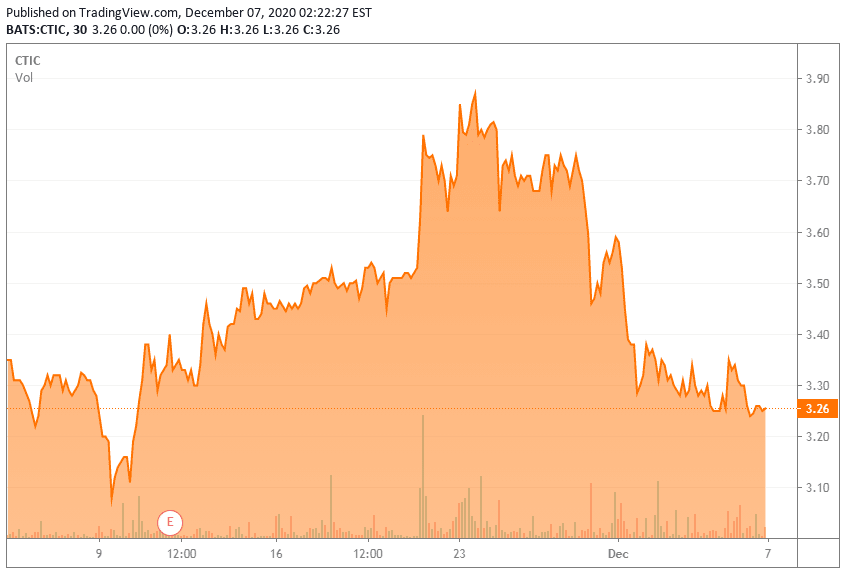
- The stock has seen strong movement recently, but there may still be catalyst-driven upside.
- Looking for more investing ideas like this one? Get them exclusively at The Total Pharma Tracker. Get started today »
I have followed CTI BioPharma (CTIC) over the years. Its principal claim to fame and potential fortune is that in a certain subset of myelofibrosis patients its lead and currently only drug pacritinib works better than Jakafi. Last year, Jakafi’s annual sales were $1.7B. The subset of patients are those with severe thrombocytopenia, roughly 25% of all MF patients. Jakafi is approved in 3 indications, and it is not clear how much it actually makes from MF. However, considering the size of the MF market itself, and Jakafi’s dominant position therein, it makes sense to assume a $300M valuation for this subset. And that’s where pacritinib comes in. If approved, it will own a major part of this market. Current market cap of CTIC is $240M. You do the math.
The stock has languished for years. Decades ago, CTI BioPharma was Cell Therapeutics, and that company also languished for years. That is another story and has little relevance to the current one. However, it is still good to see, for those who know the bit of history, that CTIC has finally started a rolling NDA submission for pacritinib in MF patients with severe thrombocytopenia (platelet counts less than 50 x 109/L). This should be completed by Q1 2021. That is a major catalyst.
Adam R. Craig, M.D., Ph.D., President and Chief Executive Officer of CTI Biopharma, said: “We have started pre-commercial activities and are planning for a commercial launch in 2021, subject to priority review.”
This statement is markedly different from what we had been hearing earlier about a launch in 2023. The difference has happened because between then and now, the company has received accelerated approval. That means they can use a surrogate endpoint in the registrational trial, like spleen volume reduction (SVR) data, get approved, and proceed to a phase 4 confirmatory trial later. That means a much quicker approval.
So, they have a priority review and expect a 2021 launch. Do they have cash for that? I think they do; they have $57M as of the September quarter, and they are currently burning roughly $40M per year based on previous year’s burn. So, they do have cash and to spare; however, I expect a dilution on completion of the NDA. I do also expect another spike, probably more modest than the one they had in October when they shot up from $1 to nearly $4 in a matter of days. Such a spike may not happen; however, if the stock can make it to $6ish – not an impossible goal given the potential – then a dilution of a few tens of millions can be absorbed by retail investors. That cash, then, could be used for commercial work. That would make sense.


