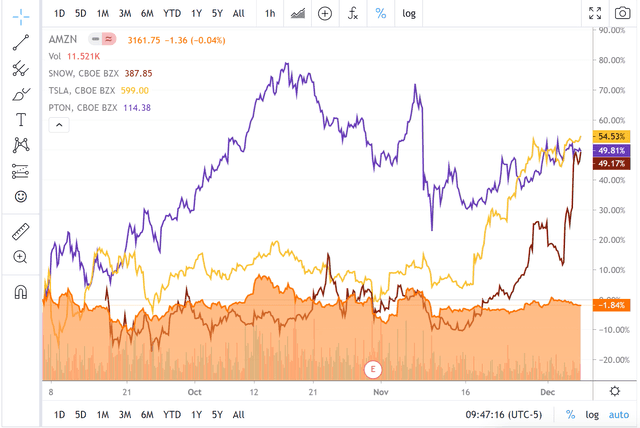
- Amazon has traded sideways for 3 months even after beating EPS estimates by $4.98 and revenue estimates by $3.54 billion in Q3 2020.
- The market isn’t valuating the companies in the same respect as overvalued highflyers can generate 40% plus returns in 3 months while AMZN grows across the board and is down.
- AMZN will continue to see tremendous growth in AWS and online retail sales as more companies make their digital transformation and as e-commerce chips away at its % of retail sales.
- Amazon is putting up double digit growth rates in many critical areas been though its on the way to becoming a $2 trillion company.
I think many would agree that Amazon (AMZN) has become one of the most essential companies throughout 2020. The amount of AMZN boxes I see delivered to the building I live in on a daily basis is astounding. AMZN’s stock has actually been a negative investment over a three-month period generating a return of -1.84% while Tesla (TSLA) is up 54.53%, Peloton (PTON) is up 49.81% and Snowflake (SNOW) is up 49.17%. I feel like investors have stopped making investment decisions based on earnings reports and financial analysis. Revenue growth isn’t the end all be all when determining a company’s value and shouldn’t be the determining factor when deciding what you’re willing to pay for a stock. I have a news flash for everyone, even though you may have been late to the party AMZN has tremendous firepower left as this $1.59 trillion company still puts up revenue increases as if it was a much smaller company. I think AMZN is a buy as there is simply no reason it can’t break out past its summer highs of $3,531.45. If AMZN was to get back to $3,531.45 it would represent an increase of 11.66% and if that occurs I don’t think the upward trend would stop there and investors could see 15-20% gains in the next leg up.
How is Amazon down since its Q3 report on 10/29 while others skyrocket?
Maybe my Achilles heel is that I read the quarterly reports, presentations, and earnings call transcripts of companies I invest in as well as companies I am interested in. I base my investment decisions on the most relevant information I can access while considering forward macro trends. It’s funny how this approach doesn’t always work out as well as just investing in the hottest IPO or growth stock. Even at what I consider an inflated IPO price I would have done better over the past three months just allocating some capital to Snowflake (SNOW). Maybe the market doesn’t put as much stock in the numbers as I do but I would rather invest in a business which I consider to be healthy and growing rather than a what if.
I don’t think the majority of the investment community took the time to read through AMZN’s Q3 report. Maybe it’s the share price that is scaring off new money flowing in and I will address that later. AMZN decimated earnings estimates yet the stock price has trended down while other companies who had lackluster Q3 reports soared. AMZN generated $12.37 earnings per share (EPS) as they generated an additional $4.98 per share than what was expected for a beat of 67.39%. AMZN beat the consensus on operating income as $4.77 billion was expected and AMZN generated $6.1 billion which was a 27.9% above estimates. On revenue which is what the market seems to be fueled by AMZN was expected to generate $92.56 billion and they produced an additional $3.54 billion which was 3.8% above the estimates. On a Year over Year ((YoY)) basis AMZN’s revenue increased by 37.3%. I think everyone should let that sink in as this isn’t a start up or a middle of the pack company. AMZN is one of the largest companies in the world and it grew their revenue YoY by over a 1/3rd yet the stock wasn’t rewarded.


