- BorgWarner posted better than expected third quarter numbers, with revenue 6% ahead of expectations and about 300bp above weighted underlying production.
- BorgWarner will be facing some renewed headwinds in Engine from declining diesel light vehicle production, but other products like dual-clutch transmissions and hybrid/EV components will help offset this pressure.
- Management attempted to reassure the Street that the debates about OEMs insourcing/outsourcing hybrid and EV components are largely noise, and the company can generate good returns on components (vs systems).
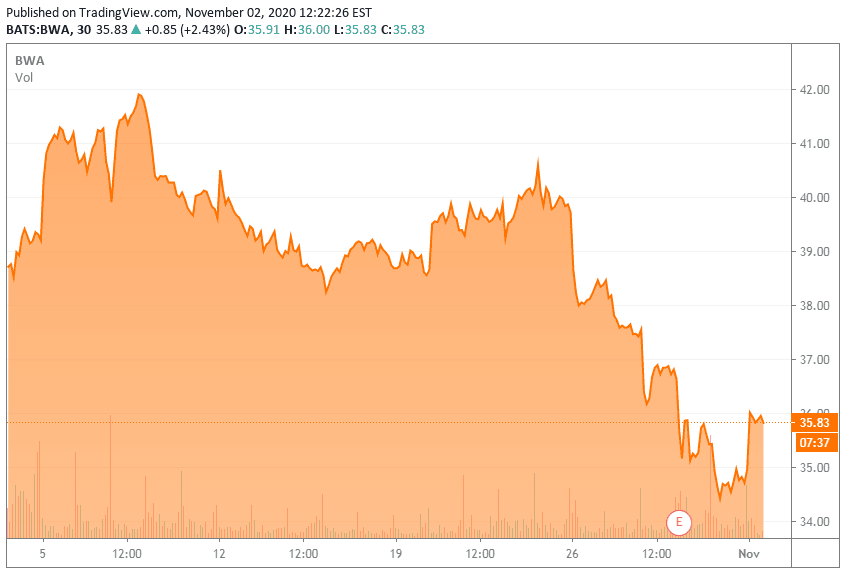
- BorgWarner shares look undervalued on this pullback, with double-digit annualized return potential.
Between internal combustion engines, hybrids, and all-electric vehicles, BorgWarner (NYSE:BWA) has an attractive and comprehensive portfolio of solutions, and I expect BorgWarner to remain one of the key suppliers to the industry through this extended transition period. There are certainly short-term risks from COVID-19 and longer-term risks tied to uncertainties in how much OEMs will in-source (and the margins they will be willing to allow to suppliers), but I remain of the opinion that BorgWarner will maintain strong content growth, allowing the company to outgrow underlying production volumes across the next decade.
When I last wrote about BorgWarner, I had some concerns that the rally might have gone a little too far too fast, and the shares have since pulled back about 15%. I’ve taken advantage of this pullback to add shares in my own account, and I believe the shares are once again priced to offer an attractive double-digit long-term total annualized return. I don’t ignore or dismiss the above-average risks here, but I believe the current price undervalues the quality of the company and its ability to leverage not only hybrid/EV content growth, but also growth from more conventional powertrains that will still be in production for some time.
A Return To Growth In A Difficult Operating Environment
The auto parts sector has, in general, done better than expected this quarter on better underlying production volumes and good cost discipline. As is often the case, though, the Street had already bid shares up in anticipation, and we’re seeing more than a few “sell the news” reactions, exacerbated by renewed worries about what rising COVID-19 case counts in the U.S. and Europe may mean for economic growth in 2021.
BorgWarner reported 2% revenue growth in the quarter, or a little less than 1% on an organic basis. That was good for a 6% beat relative to the Street, as well as about 600bp of outperformance relative to global underlying light vehicle production (or closer to 300bp on a weighted-average basis).
Growth and outperformance were driven by the Drivetrain segment, up 8%, as BorgWarner benefited from better dual-clutch transmission sales in China (contributing to a very strong 2,800bp outperformance there) and better mix in North America. Engine sales declined 4%, with BorgWarner seeing increasing headwinds as the company laps some easier comps and once again faces headwinds related to diesel content/production declines in Europe.
Gross margin declined about 60bp in the quarter, but segment income improved 4% and operating income improved 7%, beating expectations by more than 30%. Outperformance was again led by Drivetrain, up 31% with margin up 210bp, while Engine declined 7%, and margin declined 70bp.


