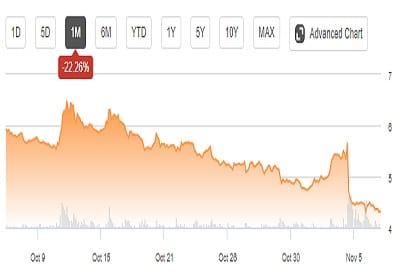
Clovis Oncology (CLVS) has become a reliable trade over the past couple of years, which has yielded some healthy returns. The stock has a history of strong sell-offs followed by buyout rumors or news stoked rallies. The recent market sell-off provided me with another opportunity to buy at a discount price just ahead of the company’s Q3 earnings on November 5th. Unfortunately, the company fell short of the Street’s expectations and the stock fell roughly 20%. In addition, the company announced a debt offering of $50M and a decision to make a major cut in their sales team. Still, Clovis has reported significant revenue growth and its flagship product, Rubraca, continues to accrue additional indications both in the U.S. and Europe. What is more, the company’s pipeline is full of impressive programs that will be fueled by a strong cash position and access to finances. As a result, I believe CLVS is worthy of speculative investment at these prices.
READ FULL ARTICLE HERE


